What Is the Tata Steel Share Price Today?
The BSE quote verified for this article is ₹174.55 at 9:34 a.m. IST on 15 October 2026. Check NSE or BSE for a later live quote.
By Dalal Street Investment Journal (DSIJ)
Tata Steel reported ₹2,32,140 crore in FY26 consolidated revenue and ₹10,886 crore in PAT. Indian operations are expanding while UK restructuring and European costs remain in focus. This review examines financials, ownership, and technical indicators.
Tata Steel was quoted at ₹174.55 on the BSE at 9:34 a.m. IST on 15 October 2026. The previously completed session NSE close was ₹174.49 on 14 October. The stock was quoted below its May 2026 high, and a price below an earlier high does not by itself indicate valuation.
| Tata Steel | Value |
|---|---|
| BSE price (15 Oct 2026, 9:34 a.m) | ₹174.55 |
| NSE closing price (14 Oct 2026) | ₹174.49 |
| Market capitalisation | ₹2,17,899 crore |
| 52-week high/low | ₹224.40 / ₹160.00 |
| Trailing P/E | 18.5x |
| Price/Book | 2.13x |
| FY26 consolidated revenue | ₹2,32,140 crore |
| FY26 consolidated PAT | ₹10,886 crore |
| Indicative dividend yield | 2.29% |
(Sources: Business Standard live quote; Screener; Tata Steel FY26 release. Valuation multiples and yield use prices around 14 to 15 October 2026.)
Established in 1907, Tata Steel is an integrated producer with iron ore mining, steelmaking and downstream products in India, as well as operations in the Netherlands, the UK and Thailand. Its product portfolio includes hot rolled and cold rolled steel, galvanised products, automotive steel, branded construction steel and tubes. Integration with domestic iron ore helps its Indian units manage part of their raw material exposure.
| Disclosed Measure | Value |
|---|---|
| India revenue | ₹1,40,302 crore |
| Consolidated revenue | ₹2,32,140 crore |
| India crude steel output | 23.43 million tonnes |
| Consolidated production | 31.67 million tonnes |
| India steel deliveries | 22.53 million tonnes |
(Source: Tata Steel FY26 Integrated Report and Results.)
The company is expanding domestic capacity and increasing the share of higher value products for automotive, engineering, infrastructure and retail customers. India produced 168.4 million tonnes of crude steel in FY26, according to IBEF.
The FY24 to FY26 period shows the sensitivity of consolidated profits to steel prices, raw material costs and European restructuring. FY24 included exceptional charges and a net loss; improvement in India and narrower overseas losses contributed to the FY26 recovery.
| Financials | FY24 | FY25 | FY26 |
|---|---|---|---|
| Revenue (₹ crore) | 2,29,171 | 2,18,543 | 2,32,140 |
| Revenue growth | Not applicable | Negative 4.6% | 6.2% |
| Reported EBITDA (₹ crore) | 23,402 | 25,802 | 34,848 |
| EBITDA margin | 10.2% | 11.8% | 15.0% |
| Reported PAT (₹ crore) | Loss of 4,910 | 3,174 | 10,886 |
(Sources: Tata Steel FY25 and FY26 official results. EBITDA margins are calculated from company reported EBITDA and turnover; figures are consolidated)
In Q1 FY27, consolidated revenue was ₹60,794 crore, EBITDA was ₹9,370 crore and PAT was ₹2,385 crore. Profit attributable to owners was ₹2,318.35 crore. India EBITDA was ₹9,908 crore, the Netherlands recorded EBITDA of €4 million, while the UK recorded an EBITDA loss of £27 million. The latest Q2 FY27 operating update, dated 7 October 2026, shows India deliveries of 5.97 million tonnes, up 7% year on year; these are provisional volumes, not Q2 earnings.
At a share price near ₹174.55, Tata Steel traded at roughly 18.5 times trailing earnings and 2.13 times book value. Return on equity of 11.7% and ROCE of 12.5%. The estimated FY26 gross debt-to-equity ratio is around 0.90x, using ₹92,382 crore in borrowings and ₹1,02,167 crore in equity capital plus reserves reported in Screener.
| Ratio | Tata Steel/Context |
|---|---|
| Trailing P/E | 18.5x |
| Price to book | 2.13x |
| ROE | 11.7% |
| ROCE | 12.5% |
| Gross debt/equity (FY26) | 0.90x |
| Dividend yield (₹4/share) | 2.29% |
(Sources: Screener; Business Standard; Tata Steel FY26 Annual Report)
For comparison, the simple average P/E of the three selected steel producers in the peer table below is about 19.1x, and their average ROCE is about 10.5%. This is a small sample benchmark, not an officially published steel sector average. Differences in captive mining, overseas losses, debt, and the earnings cycle limit direct comparisons.
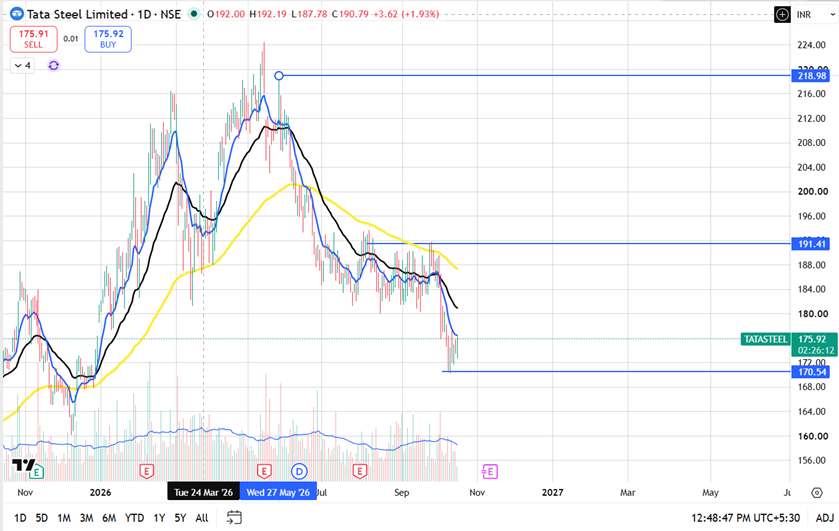
On a technical basis, the share price of Tata Steel has shown a pattern of lower highs and lower lows on a daily time frame. A near-term support level has been noted at ₹170. A resistance level has been noted at ₹191. A move beyond this level would represent a change from the current pattern of lower highs and lower lows.
As of October 15, Tata Steel is trading below its short-term, medium-term and long-term moving averages on the daily chart. On the weekly chart, the stock is trading below its 10-week and 30-week moving averages but trading above the 100-week moving average.
| Holder Category | Sep 2025 | Dec 2025 | Mar 2026 | Jun 2026 |
|---|---|---|---|---|
| Promoters | 33.19% | 33.19% | 33.19% | 32.94% |
| FIIs | 17.29% | 17.49% | 18.58% | 18.90% |
| DIIs | 26.92% | 26.98% | 26.67% | 26.44% |
| Government + public | 22.60% | 22.32% | 21.54% | 21.70% |
(Source: Screener consolidated shareholding table; the government plus public row is summed from separately disclosed classifications; rounding applies.)
Across the period, FII ownership rose 1.61 percentage points, while DII ownership eased 0.48 percentage points. These historical movements do not predict future purchases. Promoter shareholding is reported as 32.94% in June 2026.
JSW Steel and Steel Authority of India (SAIL) are included for comparison. Tata Steel’s earnings mix includes captive Indian iron ore and a larger European exposure. Multiples shown below are approximate snapshots from October 2026, not synchronised intraday quotes.
| Company | Business Focus | P/E (approx.) | ROCE |
|---|---|---|---|
| Tata Steel | India + European steel | 18.5x | 12.5% |
| JSW Steel | Integrated Indian steel | 23.9x | 11.0% |
| SAIL | Government-owned steel | 14.8x | 7.9% |
(Sources: Screener pages for Tata Steel, JSW Steel consolidated and SAIL consolidated; Tata Steel price adjusted as of October 15, 2026)
Tata Steel’s ROCE of 12.5% compares with 11.0% for JSW Steel and 7.9% for SAIL. A lower P/E does not by itself indicate valuation. EBITDA per tonne, maintenance capex, debt, product mix and potential impairment or environmental costs are factors that may be compared.
UK electric arc furnace conversion requires capital and carries execution risk; the Netherlands faces environmental, energy and regulatory investment decisions. A prolonged loss-making phase can absorb cash generated by India.
Indian producers face imported coking coal costs and changes in domestic hot-rolled coil prices. Low-priced global exports, particularly from Asia, can compress realisations even when domestic volumes grow. Changes in safeguard measures can alter the outlook.
The company reported net debt of ₹84,173 crore at June 2026. New capacity, decarbonisation spending or delayed operating recovery could constrain free cash flow. Stock prices can also fall if investors reduce the P/E or EV/EBITDA multiple applied to cyclical earnings.
Tata Steel’s operations include exposure to Indian steel consumption, captive mineral resources and a portfolio of higher value products. FY26 PAT was ₹10,886 crore against ₹3,174 crore in FY25, while Q2 FY27 India deliveries were 5.97 million tonnes, up 7% year on year. The opposing considerations are European cash requirements, commodity price volatility, and net debt of ₹84,173 crore as of June 2026.
India EBITDA per tonne, UK and Netherlands cash losses, return on expansion capital and net debt are factors linked to future results. A share price below its 52-week high does not by itself indicate valuation.
Tata Steel UK stopped blast furnace steelmaking at Port Talbot and is building a lower carbon electric arc furnace route. Its FY26 EBITDA loss narrowed to £217 million from £385 million in FY25, while Q1 FY27 showed a £27 million loss. The transition still entails execution, market, and financing uncertainty.
The Netherlands recorded EBITDA of €267 million in FY26 and €4 million in Q1 FY27 amid a temporary downstream plant shutdown. In September 2026, the Dutch government, provincial authorities and Tata Steel Netherlands extended their green steel Joint Letter of Intent to 1 March 2027; the final investment agreement remained outstanding. The division therefore poses regulatory and capital allocation risks even when volumes stabilise.
The Kalinganagar Phase II programme raised site steel capacity from 3 to 8 million tonnes per annum, bringing the reported Indian capacity to 26.1 MTPA. The company describes the expansion investment as about ₹27,000 crore. Blast furnace utilisation and downstream cold rolling and coating facilities are factors linked to automotive-grade and value-added deliveries.
On 30 July 2026, the Tata Steel Board approved a ₹33,873 crore capacity expansion at Neelachal Ispat Nigam Limited (NINL).
The 7 October 2026 operating update reported India's production of 6.21 million tonnes and deliveries of 5.97 million tonnes in Q2 FY27. Automotive and special products volumes were approximately 1.1 million tonnes, up 19% year on year. Production ramp up, product qualification, demand and working capital are factors linked to when added tonnes translate into free cash flow.
Steel spread broadly means the realised selling price of steel less the cost of inputs, including iron ore and coking coal.
IBEF reported that India imported 2.77 million tonnes of finished steel during April to July 2026, up 36.6% year on year. China and South Korea together accounted for over 60% of those imports. These trade flows are linked to global supply, which can restrain domestic prices. In contrast, rising infrastructure and manufacturing consumption can support capacity utilisation. Steel realisations and coal costs are data points that may be tracked together.
Source: Tata Steel Annual Reports, NSE, Business Standard, Screener, ET Money, IBEF, Ministry of Steel
The BSE quote verified for this article is ₹174.55 at 9:34 a.m. IST on 15 October 2026. Check NSE or BSE for a later live quote.
Consolidated revenue was ₹2,32,140 crore, reported EBITDA ₹34,848 crore, and PAT ₹10,886 crore.
Phase II lifted the site from 3 MTPA to 8 MTPA. The ramp-up of upstream and downstream assets is a factor linked to future results.
The risk factors for Tata Steel include steel pricing, imported coking coal costs, European losses and transition spending, capital intensity, debt, and valuation changes.
SEBI Registered Research Analyst (INH000006396).
Founded in 1986, Dalal Street Investment Journal (DSIJ) brings decades of experience in India’s equity markets. DSIJ's research combines fundamental analysis with price action, guided by disciplined risk management and capital preservation. They follow a structured, data-driven approach designed to help investors and traders make informed decisions beyond short-term market noise.

Share Market Latest News
Disclaimer :
Investments in securities market are subject to market risk, read all related documents carefully before investing. This content is for educational purposes only. Securities quoted are exemplary and not recommendatory.
The information on this website is provided on "AS IS" basis. Bajaj Broking (BFSL) does not warrant the accuracy of the information given herein, either expressly or impliedly, for any particular purpose and expressly disclaims any warranties of merchantability or suitability for any particular purpose. While BFSL strives to ensure accuracy, it does not guarantee the completeness, reliability, or timeliness of the information. Users are advised to independently verify details and stay updated with any changes.
The information provided on this website is for general informational purposes only and is subject to change without prior notice. BFSL shall not be responsible for any consequences arising from reliance on the information provided herein and shall not be held responsible for all or any actions that may subsequently result in any loss, damage and/or liability. Interest rates, fees, and charges etc., are revised from time to time, for the latest details please refer to our Pricing page.
Neither the information, nor any opinion contained in this website constitutes a solicitation or offer by BFSL or its affiliates to buy or sell any securities, futures, options or other financial instruments or provide any investment advice or service.
BFSL is acting as distributor for non-broking products/ services such as IPO, Mutual Fund, Insurance, PMS, and NPS. These are not Exchange Traded Products. For more details on risk factors, terms and conditions please read the sales brochure carefully before investing.
Content Partner - Dalal Street Investment Journal Wealth Advisory Private Limited
This article is for educational purposes only and should not be considered investment advice. Market investments are subject to risks. DSIJ Wealth Advisory Private Limited is a SEBI-registered Research Analyst (Reg. No: INH000006396) and Investment Adviser (Reg. No: INA000001142). Please consult your financial adviser before investing.
For more disclaimer, check here : https://www.bajajbroking.in/disclaimer
Level up your stock market experience: Scan the QR to download the Bajaj Broking App for effortless investing and trading


Access Research Backed Stock Recommendations
|
Open Your Free Demat Account
Access Research Backed Stock Recommendations
|


"Investments in securities market are subject to market risk, read all the scheme related documents carefully before investing."
"Prevent Unauthorized transactions in your Trading/Demat Account. Update your mobile numbers/email IDs with your stock brokers/Depository Participant. Receive alerts/information of your transaction/all debit and other important transactions in your Trading/ Demat Account directly from Exchange/CDSL/NSDL at the end of the day. Issued in the interest of investors."
" We collect, retain, and use your contact information for legitimate business purposes only, to contact you and to provide you information & latest updates regarding our products & services."
"KYC is one time exercise while dealing in securities markets - once KYC is done through a SEBI registered intermediary (broker, DP, Mutual Fund etc.), you need not undergo the same process again when you approach another intermediary."
"We understand that certain investment advisors may be approaching members of the public including our clients, representing that they are our partners, or representing that their investment advice is based on our research. Please note that we have not engaged any third parties to render any investment advisory services on our behalf nor are we providing any stock recommendations/tips/research report/advisory. Persons making investments on the basis of such advice may lose all or a part of their investments along with the fee paid to such unscrupulous persons. Please be cautious about any phone call that you may receive from persons representing to be such investment advisors, or a part of research firm offering advice on securities. Do not make payments through e-mail links, WhatsApp or SMS. Please do not share your personal or financial information with any person without proper verification. Always trade through a registered broker."
Bajaj Financial Securities Limited is a subsidiary of Bajaj Finance Limited and is a corporate trading and clearing member of BSE Ltd. and National Stock Exchange of India Ltd. (NSEIL), and also a Depository participant with National Securities Depository Ltd (“NSDL”) and Central Depository Services Ltd. (“CDSL”).
Bajaj Financial Securities Limited is engaged in the business of Stock Broking and as a Depository Participant.Bajaj Financial Securities Limited does not provide any advisory services to its clients. Bajaj Financial Securities Limited may share updates from time to time (through various electronic communication modes) which are sourced from public domain and the same are NOT to be construed as any advice or recommendation from Bajaj Financial Securities Limited. Client is requested to independently evaluate and/or consult their professional advisors before arriving at any conclusion to make any investment. The decision to invest shall be the sole responsibility of the Client and shall not hold Bajaj Financial Securities Limited, its employees and associates responsible for any losses, damages of any type whatsoever.
BSE Ltd. is not in any manner answerable, responsible or liable to any person or persons for any acts of omission or commission, errors, mistakes and/or violation, actual or perceived, by us or our partners, agents, associates etc., of any of the Rules, Regulations, Bye-laws of the Stock Exchange, Mumbai, SEBI Act or any other laws in force from time to time.
BSE Ltd. is not answerable, responsible or liable for any information on this Website or for any services rendered by our employees, our servants, and us.
Personal Loan, Fixed Deposit, EMI Card are provided by Bajaj Finance Limited. Bajaj Financial Securities Limited is only a distributor. These are not exchange traded products and all disputes with respect to the distribution activity, would not have access to exchange investor redressal forum or Arbitration mechanism.
No need to issue cheques by investors while subscribing to IPO. Just write the bank account number and sign in the application form to authorise your bank to make payment in case of allotment. No worries for refund as the money remains in investor's account.
Client Registration Documents (Rights & Obligations, Risk Disclosure Document, Do's & Don'ts) in Vernacular Language: BSE | NSE
If the client wishes to revoke /cancel the EDIS mandate placed by them, they can write on email us or call on the toll free number.
Advisory for Investors : NSE | BSE
We also do pro-account trading in Equity & Derivatives Segment.
Filling complaints on SCORES/SMARTODR - Easy & Quick
A. Register on SCORES/SMARTODR portal B. Mandatory details for filling complaints on SCORES/SMARTODR (i) Name, PAN, Address, Mobile Number, E-mail ID C. Benefits: (i) Effective Communication (ii) Speedy redressal of the grievances.
SEBI Registration No.: INZ000218931 | BSE Cash/CDS/F&O (Member ID: 6706) | NSE Cash/F&O/CDS (Member ID: 90177) | MCX Member ID: 57680 | DP registration No : IN-DP-418-2019 | CDSL DP No.: 12088600 | NSDL DP No. IN304300 | AMFI Registration No.: ARN – 163403 Research Analyst SEBI Registration No. INH000010043
Compliance officer:
Mr. Harinatha Reddy Muthumula
TEL: 020-48574486
Email for any investor grievances or write to us for DP related matters.
DISCLAIMER
STANDARD DISCLAIMER
Investments in the securities market are subject to market risk, read all related documents carefully before investing.
Reg Office: Bajaj Auto Limited Complex, Mumbai –Pune Road Akurdi Pune 411035. Corporate Office: Bajaj Financial Securities Limited, 1st Floor, Mantri IT Park, Tower B, Unit No 9 & 10, Viman Nagar, Pune, Maharashtra 411014. SEBI Registration No.: INZ000218931 | BSE Cash/F&O/CDS (Member ID:6706) | NSE Cash/F&O/CDS (Member ID: 90177) | MCX Member ID: 57680 | DP registration No: IN-DP-418-2019 | CDSL DP No.: 12088600 | NSDL DP No. IN304300 | AMFI Registration No.: ARN –163403.
Website: Bajaj Broking
RESEARCH DISCLAIMER
Broking services offered by Bajaj Financial Securities Limited | Registered Office: Bajaj Auto Limited Complex , Mumbai –Pune Road Akurdi Pune 411035 | Corporate Office: Bajaj Financial Securities Limited, 1st Floor, Mantri IT Park, Tower B, Unit No 9 & 10, Viman Nagar, Pune, Maharashtra 411014 | CIN: U67120PN2010PLC136026 | Research Analyst SEB I Registration No: INH000010043.
Details of Compliance Officer:
Mr. Harinatha Reddy Muthumula (For Broking/DP/Research)
Email | Contact No.: 020-4857 4486
Investment in the securities involves risks, investor should consult his own advisors/consultant to determine the merits and risks of investment.
DISCLOSURES
Disclosures under the provisions of SEBI (Research Analysts) Regulations 2014 (Regulations)
Bajaj Financial Securities Limited ("Bajaj Broking" or "Research Entity") is regulated by the Securities and Exchange Board of India ("SEBI") and is licensed to carry on the business of broking, depository services and related activities. There were no instances of non-compliance by Bajaj Financial Securities Limited on any matter related to the capital markets, resulting in significant and material disciplinary action during the last three years. This research report has been prepared and distributed byBajaj Financial Securities Limited in the capacity of a Research Analyst as per Regulation 22(1) of SEBI (Research Analysts) Regulations 2014 having SEBI Registration No. INH000010043.
DISCLAIMER
This e-mail/ short message service (SMS) may contain confidential, proprietary or legally privileged information. It should not be used by anyone who is not the original intended recipient. If you have erroneously received this message, please delete it immediately and notify the sender. The recipient acknowledges thatBajaj Financial Securities Limited or its holding and/or associated companies, as the case may be, are unable to exercise control or ensure or guarantee the integrity of/over the contents of the information contained in e-mail /SMS transmissions and further acknowledges that any views expressed in this message are those of the individual sender and no binding nature of the message shall be implied or assumed unless the sender does so expressly with due authority of Bajaj Financial Securities Limited. This message is not intended as an offer or publication or solicitation for distribution for subscription of or purchase or sale of any securities or financial instrument(s) to anyone in whose jurisdiction such subscription etc. requires prior local regulatory clearance or is contrary to the local laws of the land in any manner or as an official confirmation of any transaction. Before opening any attachments, please check them for viruses and defects.
This service / information is strictly confidential and is being furnished to you solely for your information. This information should not be reproduced or redistributed or passed on directly or indirectly in any form to any other person or published, copied, in whole or in part, for any purpose unless otherwise expressly authorised. This service / information is not directed or intended for distribution to, or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction, where such distribution, publication, availability or use would be contrary to law, regulation or which would subjectBajaj Financial Securities Limited and affiliates/ group/holding companies to any registration or licensing requirements within such jurisdiction. The distribution of this document in certain jurisdictions may be restricted by law, and persons in whose possession this document comes, should inform themselves about and observe any such restrictions.
The data would be provided to the clients on an "as is" and "where-is" basis, without any warranty. Bajaj Financial Securities Limited or its subsidiaries and associated companies shall not be liable for any delay or any other interruption which may occur in providing the data due to any reason including network (Internet) reasons or snags in the system, breakdown of the system or any other equipment, server breakdown, maintenance shutdown, breakdown of communication services or inability of the Bajaj Financial Securities Limited or its subsidiaries and associated companies to provide the data. In no event shall the Bajaj Financial Securities Limited or its holding and associated companies be liable for any damages, including without limitation direct or indirect, special, incidental, or consequential damages, losses or expenses arising in connection with the data provided by the Bajaj Financial Securities Limited or its holding and associated companies.
ADDITIONAL DISCLAIMER FOR U.S. PERSONS
Bajaj Financial Securities Limited is not a registered broker-dealer under the U.S. Securities Exchange Act of 1934, as amended (the"1934 act") and under applicable state laws in the United States. In addition, Bajaj Financial Securities Limited is not a registered investment adviser under the U.S. Investment Advisers Act of 1940, as amended (the "Advisers Act" and together with the 1934 Act, the "Acts), and under applicable state laws in the United States. Accordingly, in the absence of specific exemption under the Acts, any brokerage and investment services provided by Bajaj Financial Securities Limited, including the products and services described herein are not available to or intended for U.S. persons. This email message does not constitute an offer or invitation to purchase or subscribe for any securities or solicitation of any investments or investment services and/or shall not be considered as an advertisement tool. "U.S. Persons" are generally defined as a natural person, residing in the United States or any entity organized or incorporated under the laws of the United States. US Citizens living abroad may also be deemed "US Persons" under certain rules.
ADDITIONAL DISCLAIMER FOR CANADIAN PERSONS
Bajaj Financial Securities Limited is not a registered adviser or dealer under applicable Canadian securities laws nor has it obtained an exemption from the adviser and/or dealer registration requirements under such law. Accordingly, any brokerage and investment services provided by Bajaj Financial Securities Limited, including the products and services described herein are not available to or intended for Canadian persons.
This mailer and its respective contents do not constitute an offer or invitation to purchase or subscribe for any securities or solicitation of any investments or investment services.
DISCLAIMER FOR REPORT DISCLOSURES UNDER THE PROVISIONS OF SEBI (RESEARCH ANALYSTS) REGULATIONS 2014 (REGULATIONS)
Bajaj Financial Securities Limited ("Bajaj Broking" or "Research Entity") is regulated by the Securities and Exchange Board of India ("SEBI") and is licensed to carry on the business of broking, depository services and related activities.
This Report has been prepared by Bajaj Financial Securities Limited in the capacity of a Research Analyst having SEBI Registration No. INH000010043 and distributed as per SEBI (Research Analysts) Regulations 2014. This report does not constitute an offer or solicitation for the purchase or sale of any financial instrument or as an official confirmation of any transaction. The information contained herein is from publicly available data or other sources believed to be reliable. This report is provided for assistance only and is not intended to be and must not alone be taken as the basis for an investment decision. The user assumes the entire risk of any use made of this information. Each recipient of this report should make such investigation as it deems necessary to arrive at an independent evaluation of an investment in the securities of companies referred to in this document (including the merits and risks involved), and should consult his own advisors to determine the merits and risks of such investment. The investment discussed or views expressed may not be suitable for all investors.
This information is strictly confidential and is being furnished to you solely for your information. This information should not be reproduced or redistributed or passed on directly or indirectly in any form to any other person or published, copied, in whole or in part, for any purpose. This report is not directed or intended for distribution to, or use by, any person or entity who is a citizen or resident of or located in any locality, state, country or other jurisdiction, where such distribution, publication, availability or use would be contrary to law, regulation or which would subject Bajaj Financial Securities Limited and associates / group companies to any registration or licensing requirements within such jurisdiction. The distribution of this report in certain jurisdictions may be restricted by law, and persons in whose possession this report comes, should observe, any such restrictions. The information given in this report is as of the date of this report and there can be no assurance that future results or events will be consistent with this information. This information is subject to change without any prior notice. Bajaj Financial Securities Limited reserves the right to make modifications and alterations to this statement as may be required from time to time. Bajaj Financial Securities Limited or any of its associates / group companies shall not be in any way responsible for any loss or damage that may arise to any person from any inadvertent error in the information contained in this report. Bajaj Financial Securities Limited is committed to providing independent and transparent recommendation to its clients. Neither Bajaj Financial Securities Limited nor any of its associates, group companies, directors, employees, agents or representatives shall be liable for any damages whether direct, indirect, special or consequential including loss of revenue or lost profits that may arise from or in connection with the use of the information. Our proprietary trading and investment businesses may make investment decisions that are inconsistent with the recommendations expressed herein. Past performance is not necessarily a guide to future performance .The disclosures of interest statements incorporated in this report are provided solely to enhance the transparency and should not be treated as endorsement of the views expressed in the report. The information provided in these reports remains, unless otherwise stated, the copyright of Bajaj Financial Securities Limited. All layout, design, original artwork, concepts and other Intellectual Properties, remains the property and copyright of Bajaj Financial Securities Limited and may not be used in any form or for any purpose whatsoever by any party without the express written permission of the copyright holders.
We offer our research services to clients as well as our prospects. Though this report is disseminated to all the customers simultaneously, not all customers may receive this report at the same time. We will not treat recipients as customers by virtue of their receiving this report.
Bajaj Financial Securities Limited and its associates, officer, directors, and employees, research analyst (including relatives) worldwide may: (a) from time to time, have long or short positions in, and buy or sell the securities thereof, of company(ies), mentioned herein or (b) be engaged in any other transaction involving such securities and earn brokerage or other compensation or act as a market maker in the financial instruments of the subject company/company(ies) discussed herein or act as advisor or lender/borrower to such company(ies) or have other potential/material conflict of interest with respect to any recommendation and related information and opinions at the time of publication of research report or at the time of public appearance. Bajaj Financial Securities Limited may have proprietary long/short position in the above-mentioned scrip(s) and therefore should be considered as interested. The views provided herein are general in nature and do not consider risk appetite or investment objective of any particular investor; readers are requested to take independent professional advice before investing. This should not be construed as invitation or solicitation to do business with Bajaj Financial Securities Limited.
Bajaj Financial Securities Limited or its associates may have received compensation from the subject company in the past 12 months. Bajaj Financial Securities Limited or its associates may have managed or co-managed public offering of securities for the subject company in the past 12 months. Bajaj Financial Securities Limited or its associates may have received compensation for investment banking or merchant banking or brokerage services from the subject company in the past 12 months. Bajaj Financial Securities Limited or its associates may have received any compensation for products or services other than investment banking or merchant banking or brokerage services from the subject company in the past 12 months. Bajaj Financial Securities Limited or its associates have not received any compensation or other benefits from the Subject Company or third party in connection with the research report. Research analyst or his/her relative or Bajaj Financial Securities Limited’s associates may have financial interest in the subject company. Bajaj Financial Securities Limited, its associates, research analyst and his/her relative may have other potential/material conflict of interest with respect to any recommendation and related information and opinions at the time of publication of research report or at the time of public appearance.
Research analyst has served as an officer, director or employee of subject Company: No
Bajaj Financial Securities Limited has financial interest in the subject companies: No
Bajaj Financial Securities Limited’s Associates may have actual/beneficial ownership of 1% or more securities of the subject company at the end of the month immediately preceding the date of publication of research report.
Research analyst or his/her relative has actual/beneficial ownership of 1% or more securities of the subject company at the end of the month immediately preceding the date of publication of research report: No
Bajaj Financial Securities Limited has actual/beneficial ownership of 1% or more securities of the subject company at the end of the month immediately preceding the date of publication of research report: No
Subject company may have been client during twelve months preceding the date of distribution of the research report.
There were no instances of non-compliance by Bajaj Financial Securities Limited on any matter related to the capital markets, resulting in significant and material disciplinary action during the last three years. A graph of daily closing prices of the securities is also available at NSE
ANALYST CERTIFICATION
The analyst for this report certifies that all of the views expressed in this report accurately reflect his or her personal views about the subject company or companies and its or their securities, and no part of his or her compensation was, is or will be, directly or indirectly related to specific recommendations or views expressed in this report.
RISK DISCLOSURE ON DERIVATIVES
SEBI study dated January 25, 2023 on “Analysis of Profit and Loss of Individual Traders dealing in equity Futures and Options (F&O) Segment”, wherein Aggregate Level findings are based on annual Profit/Loss incurred by individual traders in equity F&O during FY 2021-22.
BROKERAGE DISCLAIMER
All leveraged intraday positions will be squared off on the same day. There is no restriction on the withdrawal of the unutilised margin amount. Brokerage will not exceed the SEBI prescribed limit. Visit : Pricing
MTF
As subject to the provisions of SEBI Circular CIR/MRD/DP/54/2017 dated June 13, 2017, and the terms and conditions mentioned in the lights and obligations statement issued by the TM (if applicable).
US INVESTING
International investment is not supervised by any regulatory body in India. Thus, any claim or dispute relating to such investment or enforcement of any agreement/contract /claim will not be under laws and regulations of the recognized stock exchanges and investor protection under Indian Securities Law. The account opening process will be carried out on Vested platform and Bajaj Financial Securities Limited will not have any role in it.
IPO
This should not be construed as soliciting investment. Investors’ discretion is required. Kindly consult your financial expert before investing. No need to issue cheques by investors while subscribing to IPO. Investments in securities markets are subject to market risks, read all the related documents carefully before investing.
SCREENERS
Screeners is not Exchange-approved products and any disputes related to the same will not be dealt on the Exchange platform.
SECURITIES
Securities quoted are exemplary and not recommendatory.
IPV
Account would be open after all procedure relating to IPV and client due diligence is completed.
IMAGES
The images used are only for representation purpose. Proper due diligence has been done for the images and the image is not of any artist. The same is captured from royalty free sites.
THIRD PARTY PRODUCT DISCLAIMER
Bajaj Financial Securities Limited is a distributor for Non-Broking Products/Services such as Mutual Funds, Mutual Funds SIP, IPO, Bonds, Insurance, PMS, Global Investing, any other third-party products/services. These are not Exchange Traded Products, and we are only acting as distributors. All disputes with respect to the distribution activity, would not have access to SCORES/ODR, Exchange investor redressal forum or Arbitration mechanism. Please refer to the detailed disclaimer for Third-Party Products.
As per SEBI circular no. SEBI/HO/MIRSD/MIRSD-PoD-1/P/CIR/2023/84 dated June 08, 2023, Stockbrokers are required to upstream the entire client funds lying with them to the Clearing Corporation. Based on client’s request the funds’ release request must be placed with the Clearing Corporation. Based on the internal process and cut-off timelines of the Clearing Corporation the funds will be released to the Stock Broker. In view of this new process, as specified by the regulatory and the cut-off time of Clearing Corporation/Banks processing the funds, Bajaj Financial Securities Limited cannot commit the exact time for releasing funds payout to its client. Clients are requested to note that, Bajaj Financial Securities Limited will not be responsible for any inconvenience caused to clients due to delay in release of funds payout, including fines, delayed charges, defaults, etc.